Barclays £300 Bank Switch Offer: Is It Really £300?
📋 In this article
- The Short Answer: Is the Barclays £300 Bank Switch Offer Actually £300?
- Understanding the Mechanics: How the Barclays Switch Offer Works
- The Anatomy of the Bonus: Breaking Down the £150 + £150 Structure
- Comparing Barclays with the Market: The Santander Deadline Contrast
- The Premier Alternative: Up to £600 for High Earners
- Step-by-Step Walkthrough: How to Apply Without Making Costly Mistakes
- 1. Verify Your Status
- 2. Audit Your Direct Debits
- 3. Apply In-App
- 4. Trigger the Switch & Salary
- The Hidden Pitfalls: Why People Miss Out on the Full £300
- How Bank Switching Affects Your Credit Score
- Evaluating Your Time vs. Reward: Is It Worth It?
- Frequently Asked Questions About the Barclays £300 Offer
- Can I do this switch if I already have a Barclays savings account or mortgage?
- What happens to my old bank account after the CASS switch?
- Do online payments and Apple Pay transactions count towards the 10 monthly debit card uses?
- Is the £150 initial bonus subject to UK income tax?
- What should I read next if I want to maximise my side income?
- Ready to Claim Your Switch Bonus?
- Final Verdict: Should You Switch to Barclays?
- Keep exploring MMOnline
The Short Answer: Is the Barclays £300 Bank Switch Offer Actually £300?
If you have seen the headlines screaming about the Barclays £300 bank switch offer and your immediate reaction was healthy scepticism, congratulations—you are already thinking like a seasoned money saver. When banks dangle hundreds of pounds in front of consumers to entice them over, there is invariably a catch, a labyrinth of terms and conditions, and plenty of fine print waiting to trip up the unwary. So, let’s answer the ultimate question right off the bat: Is it really £300?
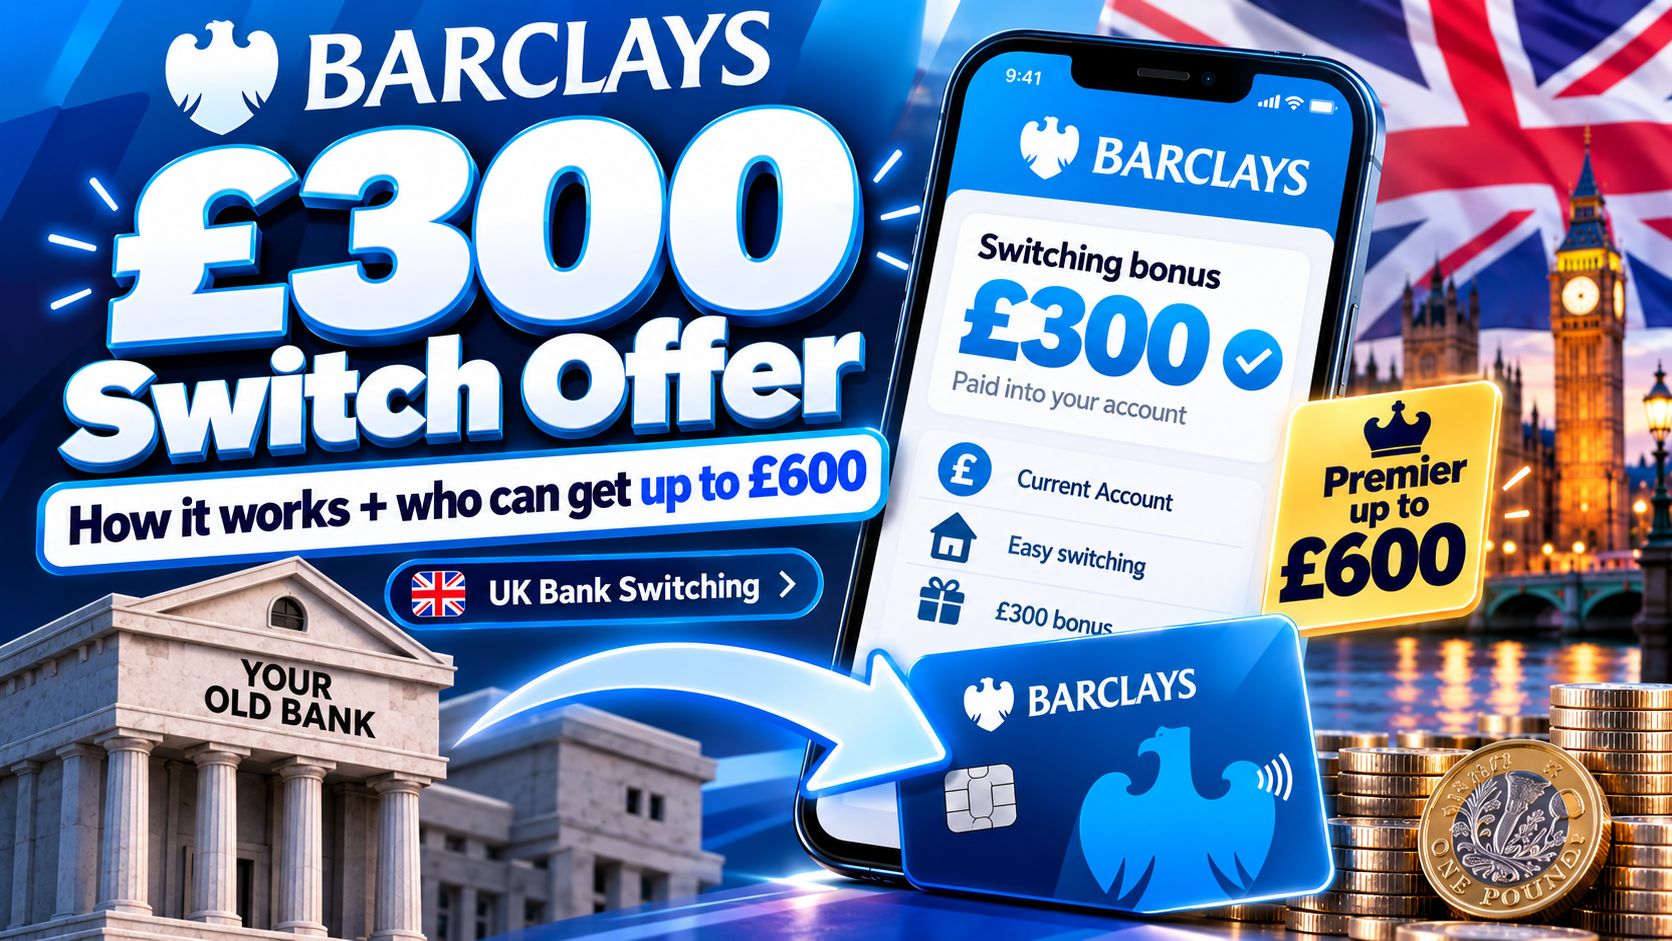
The strict, literal answer is: Yes, you can secure up to £300, but you will not get it all at once, and it requires a significant amount of ongoing housekeeping to unlock the full amount.
Here at Make Money Online, we believe in pulling back the curtain on these financial promotions so you can decide if the administrative hassle is genuinely worth your time. Before we dive into the deep end, let's establish some absolute transparency: Edward and the Make Money Online team have NOT personally completed this specific Barclays switch offer. Our analysis, critique, and breakdown are meticulously researched directly from the official terms and conditions published by Barclays for their October 2026 current account switch incentive.
Unlike a straightforward lump-sum bonus that lands in your account a few weeks after switching—such as the recent deal we analysed in our Santander £240 bank switch offer guide—Barclays has structured this promotion in a two-tier format. You get an initial £150 relatively quickly if you meet the baseline switch criteria, but the remaining £150 is drip-fed over five months via £30 monthly engagement rewards. If you slack off on your debit card usage or forget to log into the app, that second half of the prize money evaporates.
In this comprehensive guide, we are going to dissect every single clause, requirement, trapdoor, and exclusion of the Barclays £300 bank switch offer launched on 1 October 2026. We will look at how it compares to the wider market, examine the high-rollers' Premier account alternative worth up to £600, and help you determine whether your current account is better off staying put or packing its bags for a new digital home.
Understanding the Mechanics: How the Barclays Switch Offer Works
To capture the full £300, you need to understand how Barclays has engineered this incentive. Launched on 1 October 2026, this offer is designed not just to buy your custom for a month, but to turn you into an active, sticky everyday customer. The promotion may be withdrawn by Barclays at any time without advance warning—as is standard industry practice once capacity limits are reached—so timing is everything.
Let's break down the eligibility pool first. This offer is strictly targeted at new sole personal customers aged 18 or over who are UK residents. If you already hold an open Barclays current account on or before 1 October 2026, or if you have ever received a previous Barclays Current Account Switch Service (CASS) bonus in the past, you are locked out of the party. Joint accounts are completely excluded from this iteration, and applicants relying solely on a basic Barclays account will find themselves ineligible.
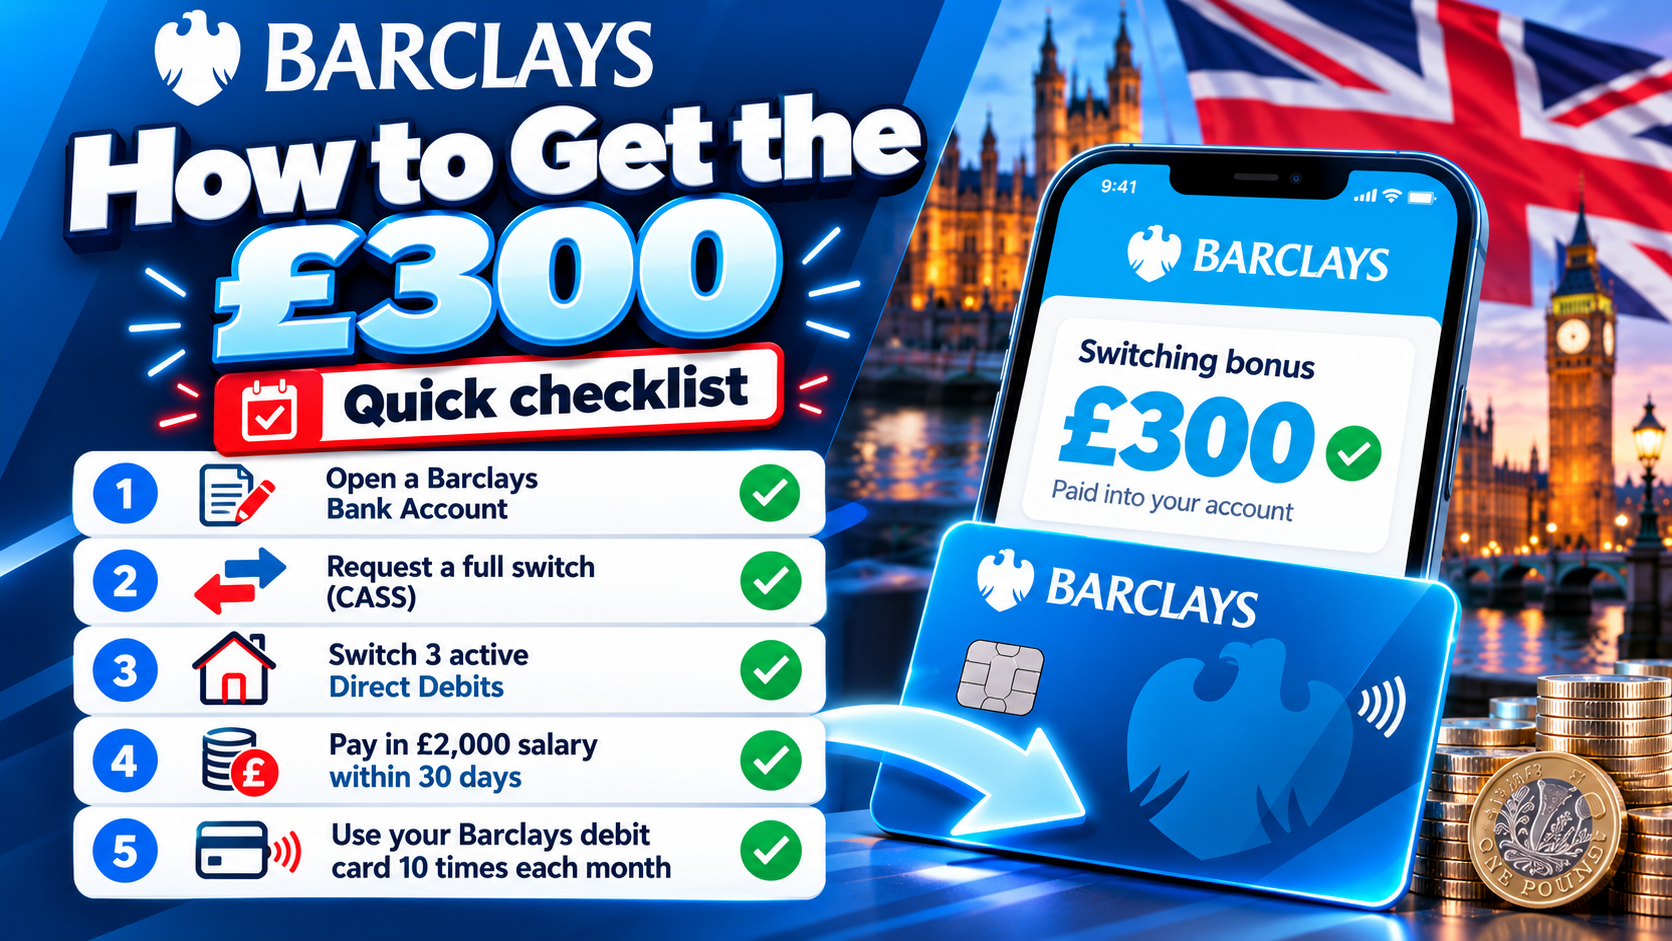
Assuming you pass the initial exclusion check, the journey begins inside the Barclays mobile app. You must submit your application directly through the app and complete the entire application process within 21 days. Once your application is accepted, you must trigger a full switch using the industry-standard Current Account Switch Service (CASS). This service guarantees that your old account is closed, your balance is transferred, and any incoming payments or Direct Debits are automatically bounced over to your shiny new Barclays account.
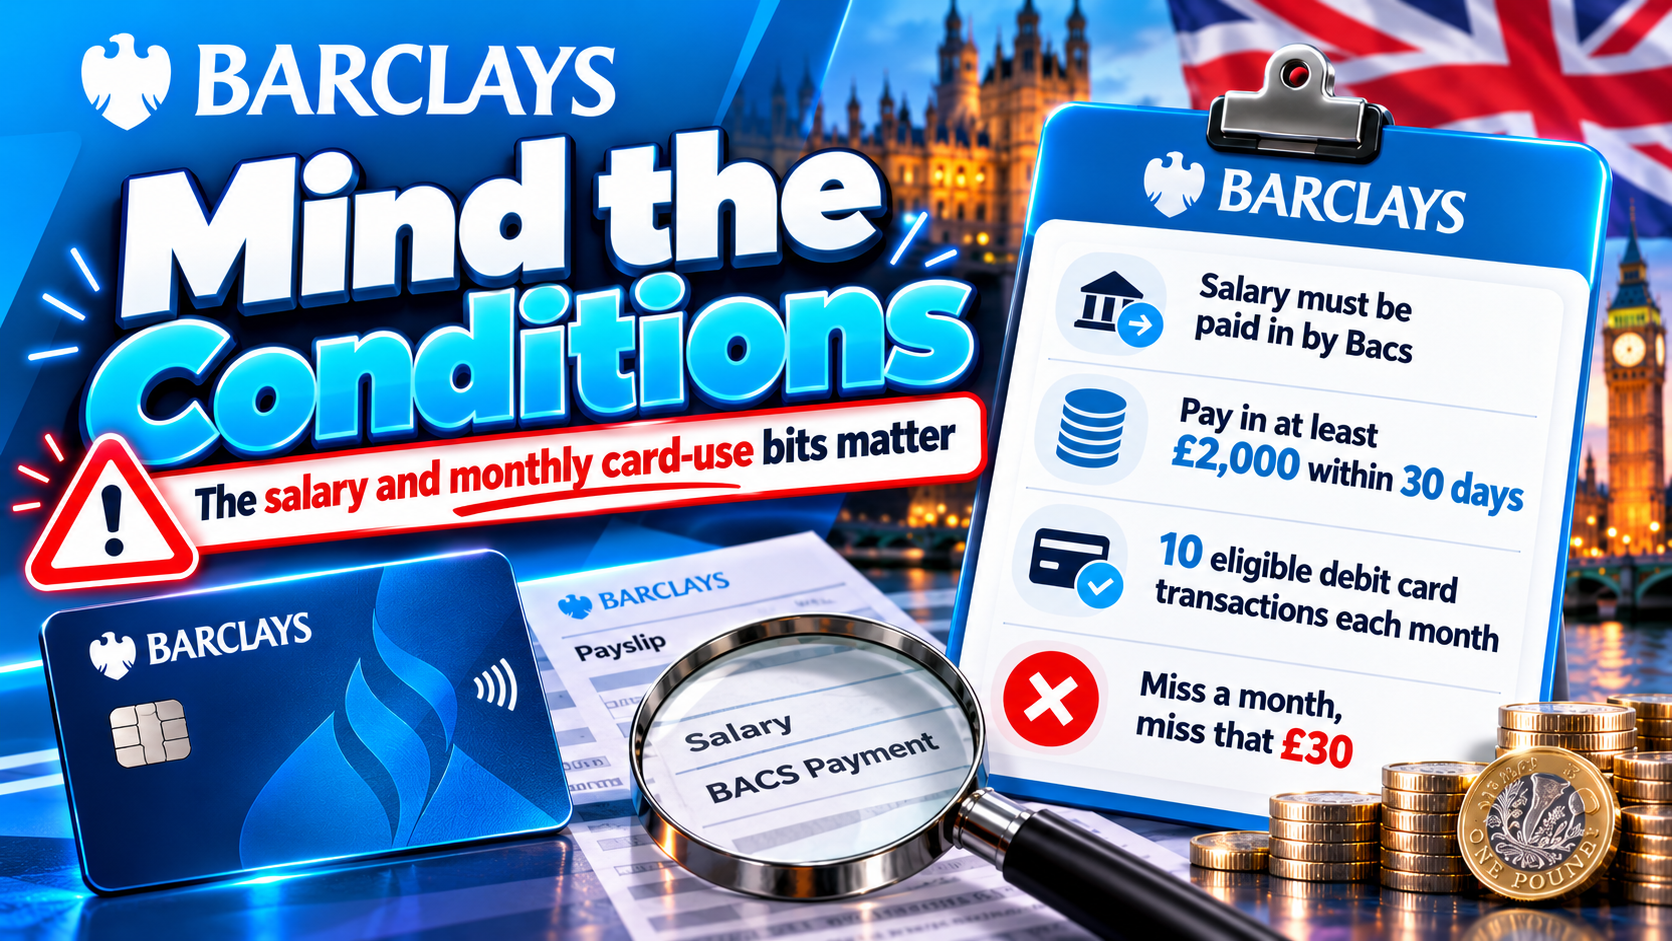
However, CASS alone is not enough to secure a single penny. Barclays has attached strict operational hoops that you must jump through within the first 30 days of initiating your switch:
- The Direct Debit Rule: Your switch request must successfully include at least 3 active Direct Debits migrating over from your old bank account. If your old account only has two Direct Debits, you will need to set up a third one on that account before initiating the CASS switch, or you will fail the eligibility criteria entirely.
- The Salary Pay-In Rule: You must pay at least £2,000 in salary or income into the new Barclays account within the first 30 days. This cannot simply be transferred from another personal account you hold in your own name at a different institution if Barclays' automated fraud and source-of-funds monitoring flags it as a round-trip maneuver; it should ideally be your genuine monthly employment payroll, pension, or legitimate self-employed business income.
The Anatomy of the Bonus: Breaking Down the £150 + £150 Structure
Once you have successfully navigated the first 30 days—your switch is complete, your three Direct Debits are live, and your £2,000 salary has landed—you enter the payout phase. This is where Barclays splits its promotional bounty into two distinct chapters.
Let's examine the first payment. The £150 initial CASS bonus is relatively straightforward. Barclays states this will hit your account within 28 working days once your eligibility has been verified following the initial 30-day window. For most switchers, this is the main event—a nice, clean cash injection that rewards you for the administrative headache of updating your bank details with your employer, utility providers, and subscription services.
However, the remaining £150 is where Barclays separates the casual bonus-chasers from everyday active users. This second tranche is distributed as up to five £30 monthly engagement rewards. To earn the £30 in any given month, you must complete a minimum of 10 eligible debit card transactions using your Barclays card.
What counts as an eligible debit card transaction? Standard retail purchases, online shopping, grocery runs, and contactless commutes generally qualify. However, cash withdrawals at ATMs, balance transfers, gambling transactions, and peer-to-peer money transfers (like sending cash to friends via PayPal or splitting restaurant bills) are typically excluded from counting towards your mandatory 10 transactions. Furthermore, if you miss the target in month three—perhaps because you were on holiday and forgot to use your Barclays card—you lose that month's £30 forever. There is no rollover or makeup mechanism.
Comparing Barclays with the Market: The Santander Deadline Contrast
Bank switching is a competitive sport, and no financial offer exists in a vacuum. To truly understand whether the Barclays £300 offer represents peak value, we must look at what else is happening across the UK banking sector right now. In fact, timing is everything in the world of current account incentives.
Only yesterday, our editorial team published a detailed deep-dive into the Santander £240 bank switch offer—an alternative promotion that many readers have been weighing up against Barclays. While Santander's headline cash figure is lower on paper (£240 compared to Barclays' £300), the structure of Santander's offer is vastly different, often requiring fewer ongoing micro-transactions to secure the full bounty.
Crucially, anyone considering their options needs to look at deadlines. The Santander offer carries a strict closing deadline of 7 October, meaning that procrastinators who read this guide too late might find the Santander door slammed shut, leaving Barclays as one of the primary heavy-hitting offers standing in the UK market.
When stacked against historical switch offers from brands like HSBC, First Direct, Nationwide, and Lloyds, the Barclays offer sits firmly in the upper tier in terms of total potential payout, but near the bottom in terms of simplicity. Most traditional switch bonuses pay out a clean lump sum within 7 to 30 days of completion and then leave you alone. Barclays is attempting a hybrid model—part acquisition bonus, part loyalty retention scheme—which requires you to stay engaged with their app and debit card for months after you've technically finished switching.
The Premier Alternative: Up to £600 for High Earners
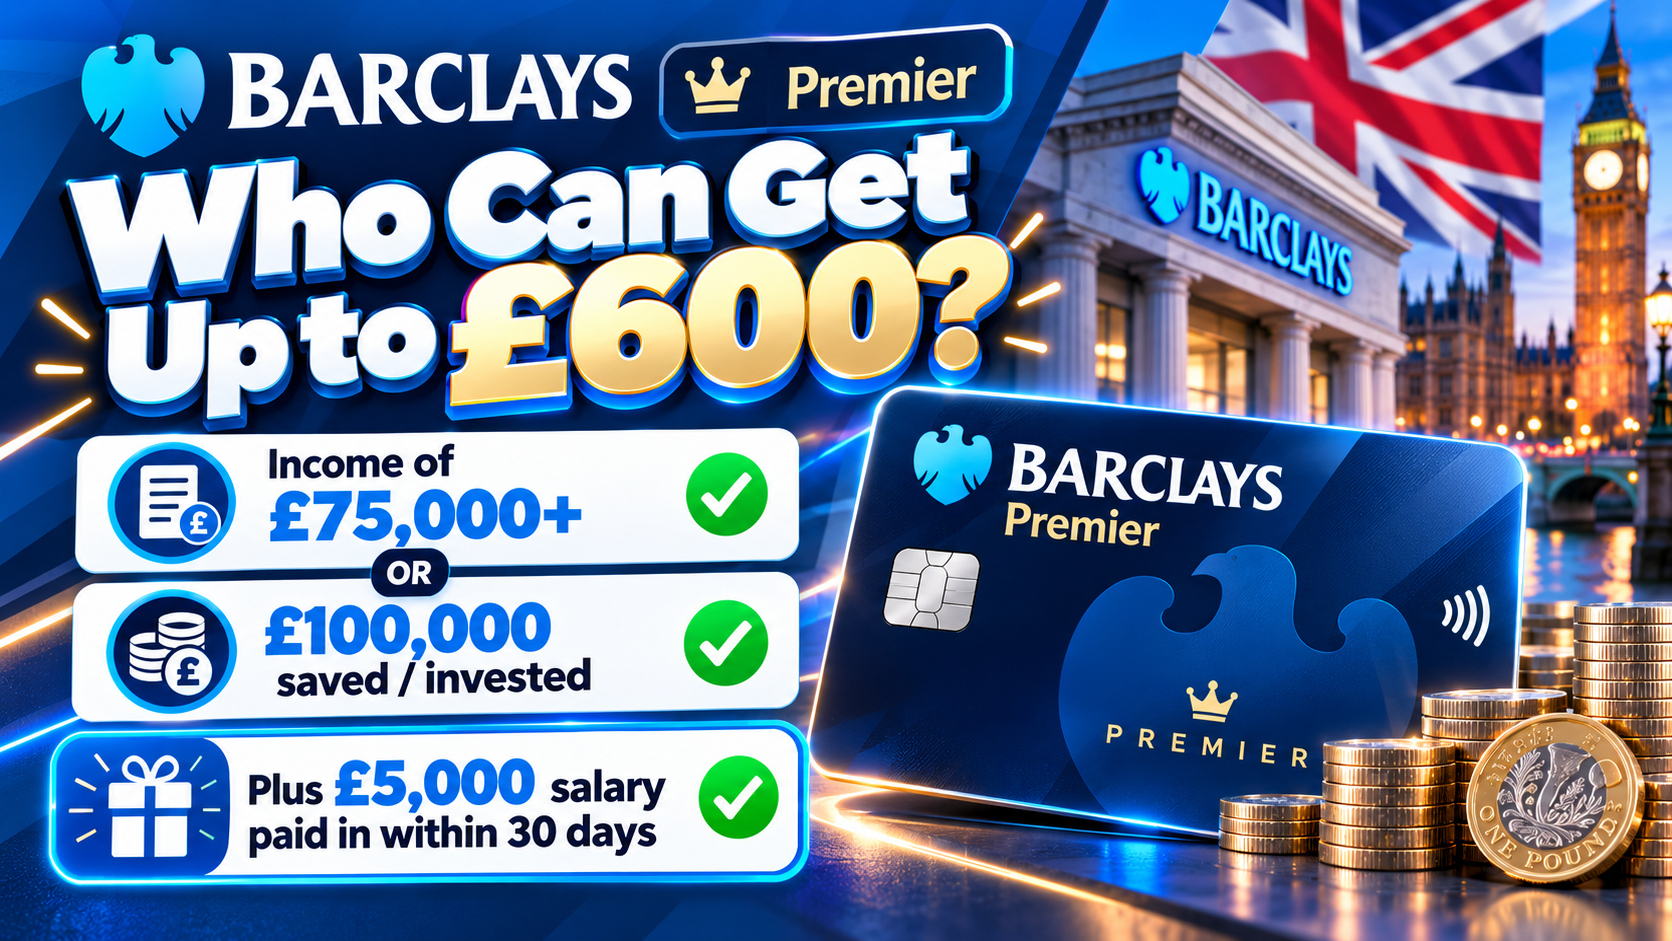
While the standard Barclays Bank Account switch offer maxes out at £300 and carries no monthly maintenance fee, high earners and affluent savers may be tempted by Barclays' heavier artillery: the Barclays Premier account switch offer, which promises up to £600.
Before your eyes light up at the prospect of doubling your switch bonus, you need to look at the strict qualifying criteria required to even open and maintain a Barclays Premier account. This is not an offer open to the general public or average wage earners. To qualify for Barclays Premier status, you must meet at least one of the following wealth thresholds:
- An annual gross income of at least £75,000 paid directly into your Barclays account; or
- At least £100,000 in eligible savings, investments, or a combination of both held with Barclays.
Furthermore, the switch criteria for the Premier £600 tier are even more demanding. The initial salary requirement within the first 30 days jumps from £2,000 to a staggering £5,000. If you do not naturally pull in a salary of £60,000+ per year (or £75,000+ for the Premier criteria), attempting to artificially cycle £5,000 through your accounts can trigger anti-money laundering flags, automated account freezes, and compliance reviews that will cause more stress than the cash bonus is worth.
For 95% of everyday consumers reading this guide on Make Money Online, the standard £300 offer is the realistic target. The Premier offer is best left to high-net-worth individuals, medical professionals, senior corporate executives, and established entrepreneurs who already meet those income brackets organically.
Step-by-Step Walkthrough: How to Apply Without Making Costly Mistakes
If you have weighed the pros and cons, checked your eligibility, and decided to proceed with the Barclays £300 switch offer, you need to execute the process with military precision. Banks are notoriously unforgiving when it comes to technicalities in their terms and conditions. If you miss a deadline by a single day or fail to transfer the exact required number of Direct Debits, their customer service agents have zero discretion to award you the bonus.
Here is a step-by-step blueprint to ensure your switch goes off without a hitch:
1. Verify Your Status
Confirm you do not already hold a Barclays current account and have never received a previous CASS bonus from them.
2. Audit Your Direct Debits
Check your current donor bank account to ensure you have at least 3 active Direct Debits ready to migrate via CASS.
3. Apply In-App
Download the Barclays mobile app and complete your standard current account application within the 21-day window.
4. Trigger the Switch & Salary
Initiate the CASS switch and ensure £2,000 in income lands in your new Barclays account within your first 30 days.
Let's elaborate on the golden rules of bank switching. When setting up your CASS switch, make sure you choose a burner or secondary account if you are worried about disrupting your primary household finances, but ensure that burner account actually has active utility, broadband, or council tax Direct Debits attached to it. Do not attempt to use an account that has zero activity; CASS requires active payment instructions to transfer successfully.
Furthermore, keep a meticulous paper trail. Take screenshots of your switch confirmation screen, note the exact date your CASS switch completes, and diarise your 30-day window for the salary pay-in. If anything goes wrong and you need to raise a dispute with Barclays customer support or the Financial Ombudsman Service, having exact timestamps and reference numbers is your strongest shield.
The Hidden Pitfalls: Why People Miss Out on the Full £300
Financial institutions love engagement rewards because human nature guarantees that a significant percentage of customers will simply forget, get lazy, or change their habits, meaning the bank never has to pay out the full advertised sum. If you want to beat the bank at its own game, you need to be aware of the most common traps that catch switchers out.
Trap 1: Forgetting the 10 monthly debit card transactions. Earning the second half of the bonus requires five consecutive months of discipline. It is remarkably easy to get used to paying with Apple Pay via your main credit card or another bank account, completely forgetting that your Barclays card needs 10 swipes or taps every single calendar month. Solution: Set a recurring calendar reminder on your phone for the 25th of every month to check your Barclays transaction count, or use your Barclays debit card for small daily purchases like morning coffees or parking tickets.
Trap 2: Assuming joint accounts qualify. As noted earlier in our official terms breakdown, this specific offer is strictly for sole personal accounts. If you and your partner attempt to switch a joint account into Barclays under this promotion, you will be rejected from the bonus pool entirely.
Trap 3: Closing the account too early. Some consumers think they can grab the initial £150 switch bonus after 30 days, close the account, and walk away. However, doing so immediately forfeits all future monthly engagement rewards and can sometimes trigger a clawback clause in the bank's terms if you breach fair usage or promotional abuse guidelines. If you want the full £300, you must keep the account open and active for at least the full duration of the engagement reward period.
How Bank Switching Affects Your Credit Score
A common question we receive from readers exploring side hustles and personal finance optimisation is: "Does switching my bank account ruin my credit score?"
The short answer is: It has a very minimal, temporary impact that usually bounces back within a few weeks or months.
When you apply for a new current account—even one with a switch incentive attached—the bank will run a hard credit search to verify your identity and assess your creditworthiness. A single hard search typically knocks a few points off your credit score temporarily. However, if the account you are opening is a standard current account without an overdraft facility (or with a modest, agreed overdraft that you do not use), the impact is negligible.
On the flip side, closing your old bank account shortens your credit history length for that specific account, which can have a minor downward effect if that old account was your oldest financial relationship. However, for the vast majority of consumers who maintain healthy credit reports with mortgages, loans, or credit cards in good standing, completing a bank switch for a £300 bonus will not prevent you from getting a mortgage or car finance in the future.
If you want to minimise any negative impact, avoid applying for credit cards, personal loans, or mortgages in the immediate 30-day window surrounding your bank switch. Let your credit file settle before making any major borrowing applications.
Evaluating Your Time vs. Reward: Is It Worth It?
Let's do some honest math. Is chasing the Barclays £300 offer actually a good use of your time? Let's break down the actual effort involved:
- Application & Setup: 20 minutes filling out the app form and providing identification documents.
- Switch Administration: 10 minutes checking Direct Debits and ensuring payroll details are ready.
- Ongoing Maintenance: 2 minutes per month ensuring you hit 10 debit card transactions over 5 months (10 minutes total).
Total time investment: roughly 40 minutes spread across half a year. For a maximum return of £300, that equates to an effective hourly rate of £450 per hour for your time. Even if you only secure the initial £150 bonus and completely forget about the monthly engagement rewards, you are still earning well over £200 per hour for half an hour of digital paperwork.
When viewed through the lens of personal finance optimisation, bank switching remains one of the highest-returning legal side hustles available to UK consumers. It requires no capital investment, no risk of losing your principal funds (unlike investing or trading), and is protected up to £85,000 by the Financial Services Compensation Scheme (FSCS).
Frequently Asked Questions About the Barclays £300 Offer
Can I do this switch if I already have a Barclays savings account or mortgage?
Yes. Having a savings account, ISA, mortgage, or credit card with Barclays does not disqualify you from the current account switch offer, provided you do not already hold an open current account with them on or before 1 October 2026.
What happens to my old bank account after the CASS switch?
The Current Account Switch Service automatically closes your old bank account on your chosen switch date. Any payments mistakenly sent to your old account are automatically redirected to your new Barclays account for a rolling period of at least 3 years, giving you ample time to update your payment details with employers and subscription services.
Do online payments and Apple Pay transactions count towards the 10 monthly debit card uses?
Yes. Purchases made online, via in-app checkouts, or through digital wallets like Apple Pay and Google Pay using your physical or digital Barclays debit card generally count towards your 10 monthly transactions, provided the merchant category is eligible.
Is the £150 initial bonus subject to UK income tax?
No. Bank switch bonuses are currently treated by HMRC as capital receipts or taxable miscellaneous income in very rare commercial edge cases, but for standard personal retail customers switching their primary current account, bank switch bonuses are tax-free. You do not need to declare them on a self-assessment tax return.
What should I read next if I want to maximise my side income?
If you are looking for other ways to boost your personal finances alongside bank switching, we recommend checking out our comprehensive Ribbon Rewards review for insights into automated cashback apps, or browsing our main Make Money Online blog for daily guides on legal side hustles and smart money management.
Ready to Claim Your Switch Bonus?
Explore more verified UK bank offers and side income guides on our platform.
Visit Make Money Online Home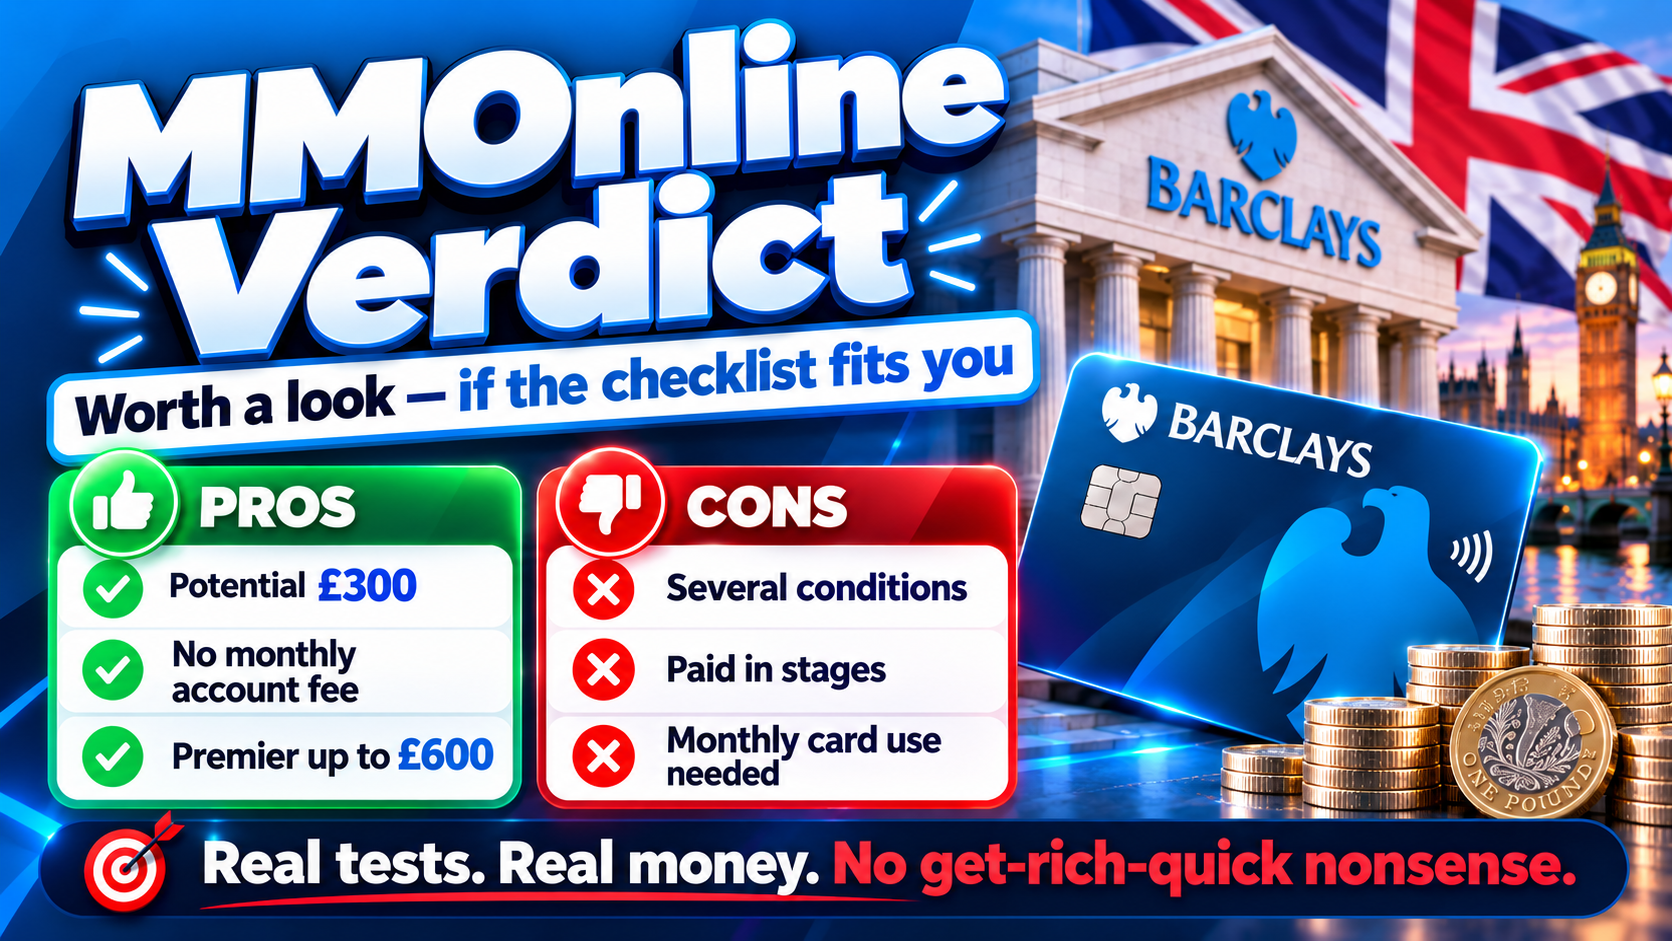
Final Verdict: Should You Switch to Barclays?
So, is the Barclays £300 bank switch offer really £300? Technically yes, but practically it demands more ongoing attention than a traditional one-and-done cash incentive. If you are someone who regularly uses your debit card 10+ times a month for groceries, travel, and shopping, capturing the full £300 is entirely achievable with zero extra effort beyond your normal spending habits.
However, if you prefer the simplicity of a single lump sum paid into your account within a few weeks—and you manage to catch offers like Santander's before their respective deadlines—you might find simpler alternatives on the market. Always weigh your personal appetite for account housekeeping against the cash reward before making your move.
Remember to check official terms directly on the Barclays website before applying, ensure your Direct Debits and salary thresholds are fully prepared, and happy switching from Edward and the team at Make Money Online!
The bonus, qualifying dates and account requirements may have changed since this article was published. Check Barclays’ current terms before switching.